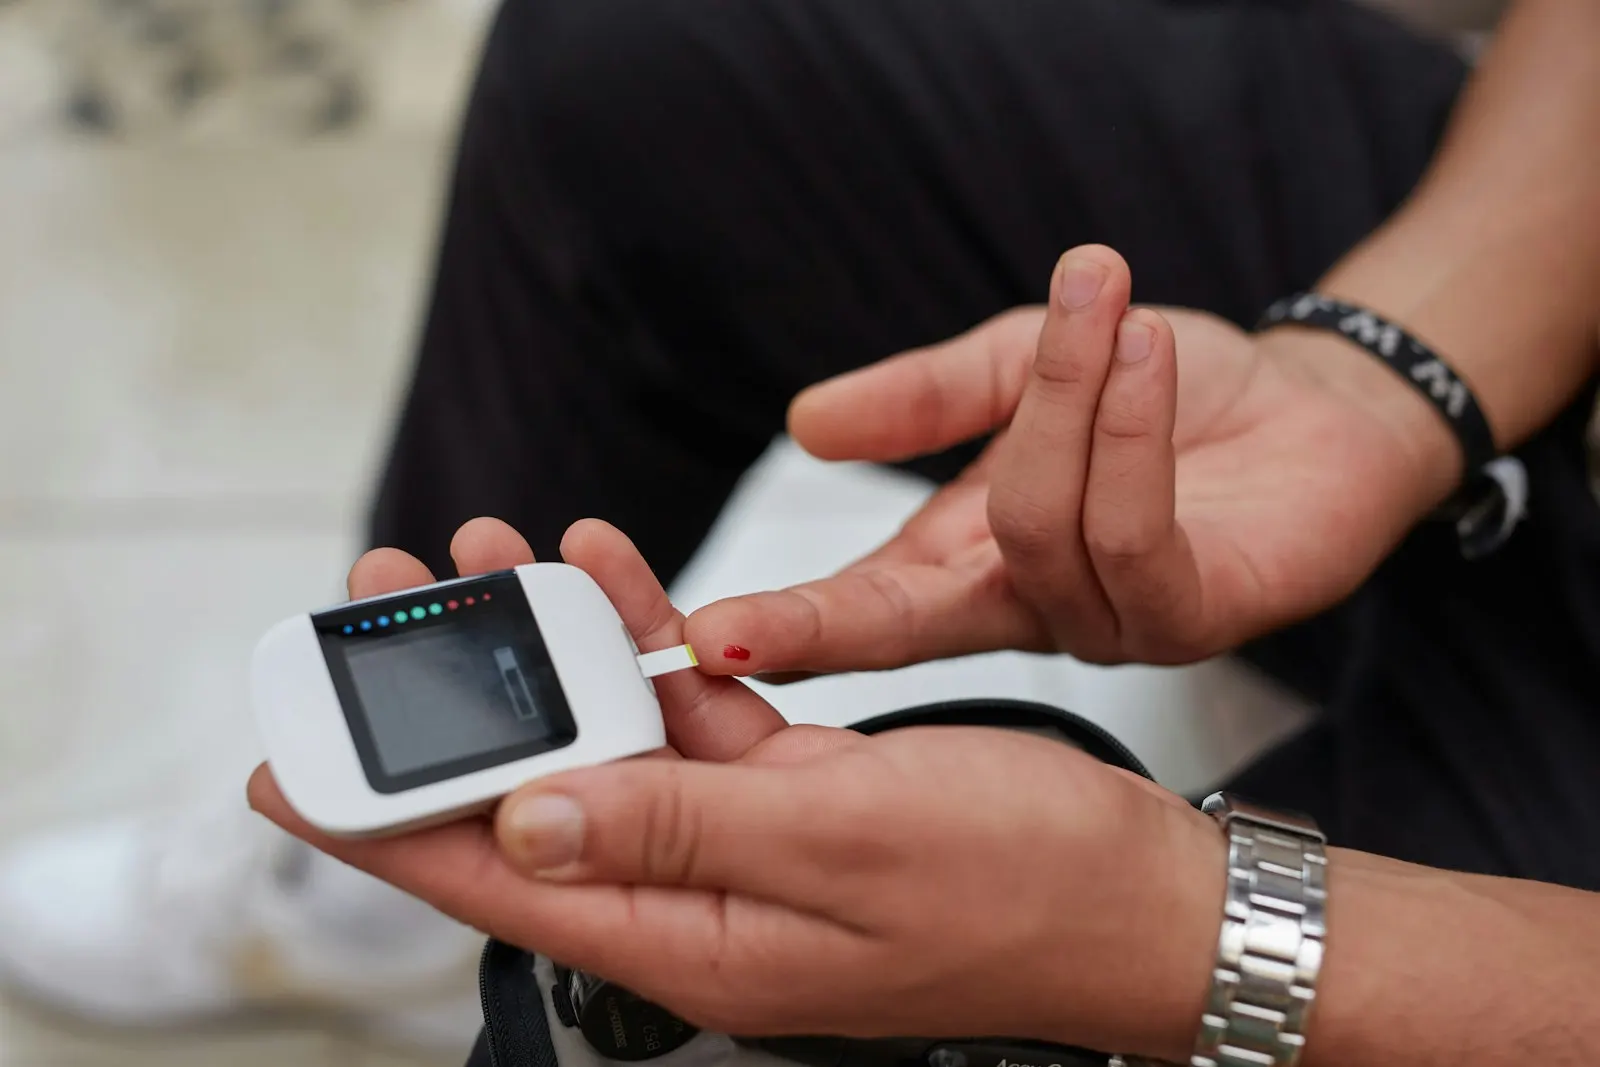
If you have diabetes, you might assume life insurance is out of reach or wildly expensive. In reality, many people with diabetes qualify for traditional life insurance, and those who manage their condition well can often get reasonable rates.
Here's what insurers look at, how your health details affect your price, and how to give yourself the best chance of approval.
Diabetes doesn't have to mean a denial. Get matched with diabetes-friendly insurers → See your real rate based on your A1C and treatment.
Can you get life insurance with diabetes?
Yes. Diabetes is one of the most common conditions insurers see, and most have clear guidelines for it. Your outcome depends far more on how well your diabetes is controlled and whether you have complications than on the diagnosis itself.
What insurers look at
When you apply, the insurer reviews your medical records and may ask for a blood and urine exam. Key factors include:
- Type of diabetes. Type 2 is generally viewed more favorably than type 1, especially when diagnosed later in life.
- Age at diagnosis. A diagnosis later in life is usually rated more favorably than an early diagnosis, because the condition has had less time to cause complications.
- A1C levels. Your recent A1C readings (average blood sugar over about three months) are one of the most important factors. Consistently lower readings help.
- Treatment. Diet and exercise alone, oral medication or insulin. Less intensive treatment generally means better rates.
- Complications. Kidney disease, nerve damage, eye disease or heart disease can significantly raise rates or affect eligibility.
- Other health factors. Weight, blood pressure, cholesterol and tobacco use all matter, and they matter more when combined with diabetes.
How your rate class is set
Insurers place applicants into rate classes that determine price. Common classes include:
- Preferred / Preferred Plus: best rates, usually for people in excellent health
- Standard: average health
- Table ratings (substandard): standard rates plus an extra percentage for higher risk
Many people with well-controlled type 2 diabetes and no complications can qualify for Standard rates. People with type 1, higher A1C readings or complications are more likely to receive a table rating, but they can often still get covered.
Your policy options
1. Fully underwritten term or whole life
This is the traditional route: a health questionnaire, medical records and often an exam. It usually offers the most coverage at the lowest price if your diabetes is well managed. For most people with diabetes, this is the place to start.
2. Simplified issue
No exam, just health questions. Approval can be faster, but coverage amounts are often lower and prices are higher. It can be a good fit if you'd rather skip an exam or need coverage quickly.
3. Guaranteed issue
No exam and no health questions. Coverage amounts are small, prices are higher, and there's usually a two- to three-year waiting period before the full benefit is paid. It's best as a last resort or for covering final expenses. See our guide to final expense insurance.
4. Group life insurance through work
Employer coverage often doesn't require health questions for a basic amount. It's a useful supplement, but it usually ends if you leave your job and is often limited to one or two times your salary.
How to improve your chances (and your rate)
- Gather your records. Have recent A1C results, a list of medications and your doctor's contact information ready.
- Keep regular checkups. Insurers like to see consistent care and monitoring.
- Work on what you can control. Improving A1C, blood pressure, cholesterol and weight can all lead to better rates.
- Don't use tobacco. Smoking combined with diabetes raises rates significantly.
- Be completely honest. Insurers verify your medical history. Leaving something out can lead to a denial or a claim being contested later.
- Work with an agent who knows the market. Insurers treat diabetes very differently. An independent agent can steer you to companies more likely to give you a good rate, instead of applying blindly.
- Ask for a review later. If your health improves significantly after you buy, some insurers will reconsider your rate class.
How much coverage should you get?
Diabetes doesn't change how much your family needs, just how much it costs. Start with your debts, income replacement needs, mortgage and education goals. Our life insurance needs worksheet walks through the math.
If you're deciding between policy types, our term vs. whole life comparison can help.
Get a quote from a professional
Finding the right insurer matters more when you have a health condition. Request a free life insurance quote, and a licensed professional can compare options and help you apply with the companies most likely to approve you, with no pressure.
Ready to see your price? Get my free life insurance quote → Takes a couple of minutes, no obligation.
Related guides
- Life insurance with high blood pressure
- No medical exam life insurance
- How much does life insurance cost? Rates by age
- Life insurance for smokers
Frequently asked questions
Can a diabetic get life insurance?
Yes. Many people with type 1 or type 2 diabetes qualify for traditional life insurance. Those with well-controlled diabetes and no complications often get competitive rates.
What A1C do life insurance companies want?
Every insurer is different, but lower, stable A1C readings lead to better rates. Readings that show good control over time are viewed more favorably than a single good result.
Is life insurance more expensive for diabetics?
Often somewhat, but not always dramatically. People with well-managed type 2 diabetes may qualify for Standard rates. Complications, early diagnosis or insulin use can increase costs.
Can I get life insurance with type 1 diabetes?
Yes, though it's typically more expensive than for type 2. Good control, regular care and no complications improve your chances.
Should I get a no-exam policy if I have diabetes?
Not necessarily. If your diabetes is well managed, a fully underwritten policy with an exam often gives you more coverage for less money. No-exam policies are convenient but usually cost more.
This article is general information, not medical or financial advice. Underwriting guidelines and pricing vary by insurer and state.